AU Bank's Altura Plus costs ₹499 a year and asks nothing about income on its product page. Its Zenith costs ₹7,999 a year and will not process an application below ₹12 lakh in annual income. That gap is the real story here, not the reward math that usually decides a card comparison. Once eligibility is settled, the fee difference closes on ordinary spending in one of the two cards and stays wide open in the other, and which of those happens depends entirely on how much of your spend already runs through dining, international transactions and grocery.
Two Cards Built for Different Stages of Spending
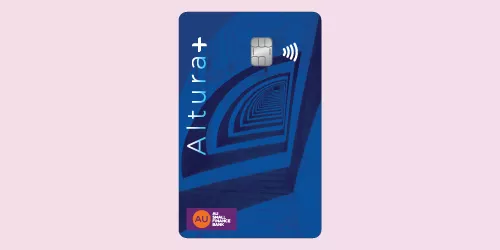
The Altura Plus is AU Bank's entry card. It carries a ₹499 joining and annual fee, waived on ₹20,000 of retail spend within the first 90 days, and again from the second year onward on ₹80,000 of annual retail spend, a threshold most cardholders clear without changing habits. It earns on two tracks that run independently: 1.5% cashback on point-of-sale retail transactions, capped at ₹100 per statement cycle, and 2 reward points per ₹100 on online transactions, worth 0.5%, with no monthly ceiling on that side. A monthly milestone adds 500 bonus points whenever retail spend in a calendar month clears ₹20,000. AU Bank publishes no minimum income requirement for this card.
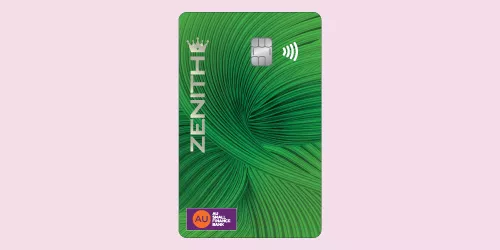
The Zenith sits several tiers up. Its ₹7,999 joining and annual fee is waived in year one only on ₹1,25,000 of retail spend within 90 days, and from year two on ₹5,00,000 of annual retail spend. Applicants need at least ₹12 lakh in annual income to be considered at all. What the fee buys is a 5-points-per-₹100 rate, worth 1.25%, on dining at standalone restaurants, international transactions and grocery or departmental store spend, capped at 5,000 points per statement cycle. Every other retail purchase earns 3 points per ₹100, worth 0.75%.
Side by Side
| Metric | AU Bank Altura Plus | AU Bank Zenith |
|---|---|---|
| Joining and annual fee | ₹499 + taxes | ₹7,999 + taxes |
| Fee waiver (Year 2 onward) | ₹80,000 annual retail spend | ₹5,00,000 annual retail spend |
| Minimum income | Not publicly stated | ₹12 lakh a year |
| Base reward rate | 1 point per ₹100 (POS, past the cashback cap) | 3 points per ₹100 |
| Accelerated rate | 1.5% cashback on POS (capped ₹100/cycle); 2 points per ₹100 online | 5 points per ₹100 on dining, international, grocery |
| Welcome benefit | ₹500 voucher on ₹10,000 spend in 60 days | ₹1,000 voucher plus 10,000 points on ₹1,00,000 spend in 60 days |
| Airport lounge | None (2 railway lounge visits a quarter) | 2 domestic (₹50,000/quarter spend-gated) + 2 international via Priority Pass |
| Foreign currency markup | 3.49% | 1.99% |
Where the Fee Gap Actually Closes
The ₹7,500 difference in annual fee looks large until it is measured against what the Zenith earns back. On its three accelerated categories, the rate advantage over the Altura Plus's online rate is 3 points per ₹100, worth 0.75% more. Spending ₹1,00,000 a month through dining, international transactions and grocery, the level at which the Zenith's own monthly cap on those categories is reached, recovers close to ₹9,000 a year in incremental reward value over the Altura Plus's 2-point online rate, before either card's welcome benefit is counted. For a spender who already routes six figures a month through those three categories, that clears the fee gap on its own.
Below that spend level, the Zenith's fee is a drag the Altura Plus never carries. A cardholder spending ₹40,000 a month across dining, international and grocery earns roughly ₹6,000 a year at the Zenith's accelerated rate, against a ₹7,999 fee before any waiver applies. The Altura Plus, run through its cashback and online tracks at the same spend, costs at most ₹499 and is waived entirely past ₹80,000 of annual retail spend. The math favors the Zenith only at the spend level its own accelerated categories are built to reward, not at the spend level most applicants actually run.
What ₹12 Lakh of Income Buys
Income eligibility is not a formality here. It is the first filter, and it removes the Altura Plus's usual applicant from contention before reward rates matter at all. The Zenith's ₹12 lakh income floor already narrows its pool to earners for whom ₹40,000 to ₹1,00,000 a month in dining, travel and grocery spend is a realistic pattern rather than a stretch, closer to the applicant base for premium and super-premium cards than to the Altura Plus's.
For that narrower pool, the Zenith adds two lounge programmes the Altura Plus does not carry: 2 international visits a quarter through Priority Pass, with no spend condition attached, and 2 domestic visits a quarter that AU Bank gated behind ₹50,000 of quarterly spend starting April 10, 2026. The Altura Plus's own travel perk, 2 railway lounge visits a quarter at five stations, reads modestly next to that. It also costs nothing beyond the ₹499 fee and asks for no income proof to get it.
The Income Line Decides It First
Ask which AU Bank card earns more, and the real answer runs through one question before it runs through reward math: does ₹12 lakh in annual income already describe you. Below that line, the Zenith is not an option regardless of how the accelerated rate compares, so the Altura Plus's cashback and uncapped online points against a ₹499 charge simply are the answer. Above that line, the question changes to whether ₹1,00,000 a month already moves through dining, international transactions and grocery. If it does, the Zenith's 5-point rate and its lounge programmes are worth the fee. If it does not, the Altura Plus still earns a reasonable return without asking for proof of either number.
There is no reader whose income and spending both sit in the narrow gap where this stays a close call. The two cards were built for different stages of the same relationship with AU Bank, and eligibility settles the question before the rewards table ever needs to.
Put the Altura Plus and Zenith side by side for the full fee, cap and rate table.
Sources
Frequently asked
Which AU Bank credit card earns more, Altura Plus or Zenith?
It depends which one you can apply for. The Zenith earns more per rupee, 5 reward points per ₹100 (1.25%) on dining, international transactions and grocery, against the Altura Plus's 2 points per ₹100 (0.5%) on online spends and 1.5% cashback on POS retail capped at ₹100 a cycle. But the Zenith needs ₹12 lakh in annual income to apply, and its ₹7,999 fee only pays for itself once monthly spend across those three categories runs close to ₹1,00,000. Below that income and spend level, the Altura Plus is the only card on the table, and at its ₹499 fee it is a reasonable one.
What is the minimum income required for the AU Bank Zenith?
₹12 lakh in annual income. AU Bank does not publish a minimum income requirement for the Altura Plus.
How much do I need to spend for the AU Bank Zenith's fee to make sense?
Close to ₹1,00,000 a month across dining at standalone restaurants, international transactions and grocery or departmental stores, the level at which the Zenith's own 5,000-point monthly cap on those categories is reached. Below that, the ₹7,999 fee is a bigger drag than the accelerated rate makes up for, even after the annual fee waiver at ₹5,00,000 of yearly retail spend.
Does the AU Bank Altura Plus offer airport lounge access?
No. It offers 2 complimentary railway lounge visits a quarter at five stations (New Delhi, Kolkata Sealdah, Ahmedabad, Jaipur and Agra) under the VISA railway lounge programme. The Zenith offers 2 international lounge visits a quarter through Priority Pass with no spend condition, plus 2 domestic visits a quarter that AU Bank gated behind ₹50,000 of quarterly spend from April 10, 2026.
Card devaluations, reward maths, and rate changes the day they land.
Follow on X
Reader comments
No comments yet. Share your experience with this card below — the first useful comment helps every reader after you.
Comments are moderated before they appear. Share your real experience with a card — what worked, what didn't, what the bank told you. We don't publish promotional content, referral links, or personal financial details. Keep it useful for other readers.