A 1.5% cashback rate and a 0.25% reward rate are two different cards wearing the same four digits. The AU Bank Altura Plus pays the first number for about ₹6,667 of point-of-sale spend in a statement cycle. Past that line, it pays the second number, on every rupee, for the rest of the month.
Overview
| Metric | Detail |
|---|---|
| Issuer | AU Small Finance Bank |
| Type | Entry-level, lifetime-fee-waivable |
| Headline rate | 1.5% cashback on POS retail, capped at ₹100/cycle |
| Post-cap rate | 0.25% (1 Reward Point per ₹100) |
| Online rate | 0.5% (2 Reward Points per ₹100), uncapped |
| Annual fee | ₹499, waivable |
| Income proof | Not stated as required |
| Lounge | Railway only, 2 visits/quarter |
What the headline 1.5% actually covers
The Altura Plus pays 1.5% cashback on point-of-sale retail transactions, the kind swiped or tapped at a physical merchant. That rate is capped at ₹100 per statement cycle, which arrives, on our calculation, at ₹6,667 of POS spend in that cycle.
Spend less than that and the 1.5% is the real number. A cardholder running ₹5,000 a month through POS earns ₹75, the full 1.5%, no catch. That is a genuinely competitive rate for a card with no income requirement.
The catch is what happens on the next rupee.
The cliff, in rupees
Cross ₹6,667 of POS spend in a cycle and the cashback cap is used up. Every POS rupee after that earns 1 Reward Point per ₹100, worth ₹0.25 per point, a 0.25% return. That is a sixth of the headline rate, not a gentle taper.
Run the numbers at ₹15,000 of monthly POS spend. The first ₹6,667 earns the full ₹100 cashback. The remaining ₹8,333 earns about 83 points, worth roughly ₹21. Total value: about ₹121 on ₹15,000, a blended 0.81%, on our calculation, well below the 1.5% the card advertises.
Online retail spend sits on its own uncapped track: 2 Reward Points per ₹100, worth 0.5%, with no monthly ceiling. It is the better fallback once POS spend clears the cashback cap, but it is still a third of what the card pays below it.
The fee line nobody puts next to the cap
In Year 1, the ₹499 joining fee is waived on ₹20,000 of retail spend within 90 days. From Year 2, the ₹499 annual fee is waived on ₹80,000 of retail spend across the year, which averages to ₹6,667 a month.
That is, on our calculation, almost the exact spend level that maxes the cashback cap. Spend enough to clear the fee waiver every year and the card has already stopped paying its best rate for most of that same spend. Spend less, and the fee comes due on a card that never reached its headline number either. There is no spend band where this card is both free and earning at 1.5% on everything.
A monthly milestone adds 500 bonus Reward Points, worth ₹125, whenever retail spend in a calendar month clears ₹20,000. The welcome offer pays a ₹500 voucher on ₹10,000 of spend within the first 60 days.
What else is on the card
The Altura Plus states no minimum income, unlike most cards in its category, and allows self-employed applicants. There is no stated maximum credit-limit tier tied to income, because there is no income floor to tier against. That makes it a reasonable first card, separate from how its cashback math works out.
Lounge access is railway only: 2 complimentary visits a quarter under the VISA programme, at New Delhi, Kolkata Sealdah, Ahmedabad, Jaipur and Agra. There is no airport lounge benefit at any spend level, and that is worth knowing before anyone picks this card expecting one. A 1% fuel surcharge waiver applies, though AU Bank's public terms do not state a per-transaction range for it.
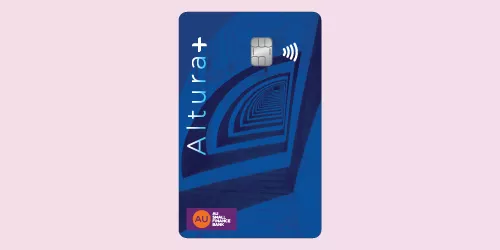
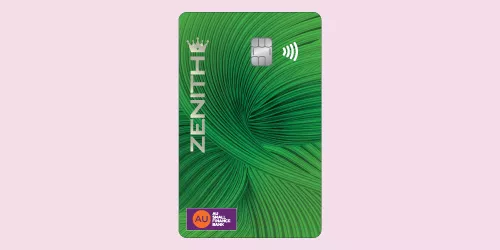
Readers comparing this card against AU Bank's premium Zenith should read our Altura Plus vs Zenith comparison, which runs the same fee-versus-spend math against a card that needs ₹12 lakh of annual income to apply for. For the mechanics of a cashback cap in general, our explainer on how credit card cashback works covers the same cliff this card produces, in the general case.
The bottom line, cap included
3.0 out of 5. The Altura Plus is a fair ₹499 card for a reader with no income proof to offer and modest, steady POS spend near ₹6,000 to ₹7,000 a month. Below that line, the 1.5% cashback is real and the fee is easy to waive.
Above it, the card quietly becomes a different product: a 0.25% to 0.5% earner with a railway-only lounge perk, carrying the same ₹499 fee line as before. That is not a reason to avoid the card outright, but it is a reason to size it to actual spend rather than to the number printed on the offer page.
Disclosure: this post contains affiliate links. If you apply through them we may earn a commission, at no extra cost to you. Our editorial view is independent of that. #ad
Featured offer · Federal Bank Scapia Credit Card
Apply free. Then refer friends for a Tanishq Gold e-gift card worth up to ₹1,00,000.
Frequently asked
What is the cashback cap on the AU Bank Altura Plus?
₹100 per statement cycle on point-of-sale retail spend, at a 1.5% rate. That ceiling is reached at roughly ₹6,667 of POS spend in a cycle. Beyond it, POS spend earns 1 Reward Point per ₹100, worth 0.25%, with no further monthly ceiling on that lower rate.
How do you get the AU Bank Altura Plus annual fee waived?
In Year 1, the ₹499 joining fee is waived on ₹20,000 of retail spend within 90 days of card setup. From Year 2 onward, the ₹499 annual fee is waived on ₹80,000 of retail spend in the previous card-anniversary year, which averages to about ₹6,667 a month.
Does the AU Bank Altura Plus earn well on online spends?
Online retail transactions earn 2 Reward Points per ₹100, worth 0.5%, with no monthly cap. That is better than the 0.25% the card pays on POS spend once the cashback ceiling is used up, but still a third of the card's headline 1.5% cashback rate.
Does the AU Bank Altura Plus offer airport lounge access?
No. It offers 2 complimentary railway lounge visits per quarter under the VISA railway lounge programme, at five stations: New Delhi, Kolkata Sealdah, Ahmedabad, Jaipur and Agra. There is no airport lounge benefit on this card.
Card devaluations, reward maths, and rate changes the day they land.
Follow on X
Reader comments
No comments yet. Share your experience with this card below — the first useful comment helps every reader after you.
Comments are moderated before they appear. Share your real experience with a card — what worked, what didn't, what the bank told you. We don't publish promotional content, referral links, or personal financial details. Keep it useful for other readers.