Why does an application that clears every published criterion still come back declined? The age sits inside the band, the income is above the stated floor, the documents were complete, and the answer is a no with no reason attached.
Because the published criteria were never the decision. They are a filter, the part an issuer commits to in writing so an applicant can rule themselves out before filling a form. The approval happens after that filter, inside a model no Indian bank describes in public, running on inputs that appear on no product page.
What the published criteria actually filter
Across the 86 active cards in our catalogue carrying recorded eligibility terms, counted on 7 September 2026, the readable half of the test comes down to age, a stated minimum annual income, employment type, and occasionally a bureau score floor.
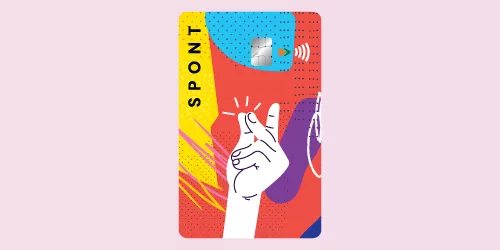
The income spread is far wider than the category language suggests. The lowest floor on record is ₹1.2 lakh a year on the AU Spont, roughly ₹10,000 a month; the highest is ₹30 lakh on the AU Bank Zenith+, with the IDFC FIRST Mayura and the American Express Platinum Charge Card both at ₹25 lakh. Fourteen active cards state no income floor at all, which is a different product rather than a generous one: most are secured, with the line drawn from a fixed deposit instead of from proven earnings.
Age bands are not uniform either. Sixty-one of those cards open at 21 and twenty-four at 18. The upper bound splits three ways rather than two: 65 on forty-four cards, 60 on twenty-seven, and 70 on thirteen: ten of the Axis Bank range, both American Express records, and the AU NoMo. Two cards sit outside all three bounds: the Stable Money Suryoday card runs 18 to 80, and the BOB Eterna accepts nobody under 25 or over 55.
Employment type is rarely the barrier it is made out to be. Exactly one active card in our catalogue, the Kredit.Pe Yes Bank ACE, is salaried-only. Published score floors are rarer still: three records carry one, SBI Card Miles and Jupiter Edge+ CSB at 700 and HDFC Regalia Gold at 750. Every other issuer reads the credit file without committing to a public number, which is why a file that clears one bank's internal bar gets declined at the next.
The same card, two rulebooks depending on how income is proved
Where eligibility does bite for a self-employed applicant, it bites through the document rather than the amount.
Take the Shoppers Stop HDFC Bank card. A salaried applicant needs ₹20,000 a month in net income, which annualises to ₹2.4 lakh. A self-employed applicant needs an ITR above ₹6 lakh, two and a half times the same card's salaried bar, and the age band shifts with it: 21 to 60 for salaried, 21 to 65 for self-employed. HDFC MoneyBack+ pairs a ₹20,000 monthly floor with the same ITR test, but its ₹20,000 is gross rather than net and its record carries one flat 21 to 60 band. The split age band is the Shoppers Stop card's alone.
A salary slip is a current document and an ITR is a lagging one, so a consultant whose income doubled last year is assessed on the year before it. An applicant with genuine income but no filed return has no route through the income test at all, whatever the bank statement shows.
Nothing above is what decides the application
The filter narrows the pool. What picks from it is a risk assessment the applicant never sees, running on inputs that are not secret so much as undisclosed.
Enquiry velocity is the input applicants damage most often and understand least. Every formal application places a hard enquiry on the credit report, and that record persists whether the outcome was an approval, a decline or a withdrawal. A cluster of them inside a few weeks describes someone working through a list, and the next lender reads the cluster rather than the intention behind it.
Unsecured exposure is assessed across lenders, not per bank. Card limits sanctioned elsewhere, personal loans and buy-now-pay-later lines all sit on the same report, and a limit counts against an applicant even when the card has never been used. A file can carry a spotless repayment record and still be turned down because the total line already extended looks large against the income declared.
Then there is the internal model, which nobody outside the bank can audit. It is why our HDFC MoneyBack+ analysis records that the card is frequently issued lifetime free to applicants holding a pre-approved offer, on terms the same bank will not extend to a walk-in application for the identical product.
A pre-qualification check and a real application are different events
Two things get called an eligibility check and only one leaves a mark. A soft pre-qualification, run by an issuer against its own customer base or by an aggregator against a bureau, tests a file without recording an enquiry other lenders will read. A formal application is a hard enquiry, recorded whatever happens next.
The distinction matters because the strongest route into a card is usually the pre-approved one. Our HDFC Millennia analysis notes, anecdotally, that pre-approved offers surface in the net banking dashboard within about 90 days of salary credits starting, and that they convert at a far higher rate than cold applications. Banking where the salary lands hands the issuer the income verification it would otherwise have to ask for.
Anything inside a bank's own app that says "pre-approved" has already cleared some version of the model. A generic "check your eligibility" button on an aggregator page has not, and reading it as an approval is how applicants end up with three enquiries in a fortnight.
What a decline actually costs
Less than most people fear, and more than the bank tells them. The decline is not itself reported: bureaus record the enquiry, not the outcome, so no future lender is told that an application failed. What is visible is the pattern, and the pattern is what an applicant controls.
A decline notice seldom names the specific input that failed, which leaves the credit report as the only document an applicant can actually interrogate. What has improved is the speed of the repair: the Reserve Bank required lenders to report credit information to the bureaus fortnightly rather than monthly with effect from 1 January 2025, so a corrected file reaches the next lender faster than it used to. The practical route to a reason is the credit report itself, read line by line against what was submitted.
The route that skips the income question entirely
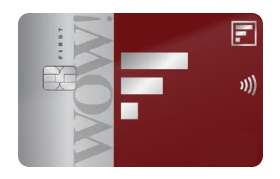
For a file that keeps failing at Stage 2, the productive move is a card that does not run Stage 2 the same way. Deposit-backed cards issue against a fixed deposit instead of an income assessment. The Stable Money Suryoday card asks for no income proof and runs an age band of 18 to 80. The IDFC FIRST WOW! is secured by a ₹20,000 fixed deposit, sets the limit to match it, and reports to the bureaus from the first month, which is the part that matters: the account builds precisely the record the unsecured application was missing. The full secured-card shortlist and what each one costs sits separately.
A thin file is not a bad file, it is an empty one, and a single card used properly fills it faster than several applications do. Anyone applying in their first months of a salaried job is there by definition rather than by fault.
The ninety days after a no
Stop applying first. Every further attempt in that window adds an enquiry to a report already being read as an applicant under pressure, and none of them change an input the model looks at.
Pull the credit report next, from the bureau rather than from an app that summarises it, and read it against what was filed: the total sanctioned limit across every unsecured line, any account showing as overdue or settled, and whether the declared income is one the documents on file can support.
Then weigh closing what is idle. An unused card with a live limit consumes exposure the next issuer would otherwise have room to extend, and it is one of the few levers here that can be pulled in an afternoon. Closing also strips that limit out of the utilisation denominator, though, and shortens the average age of the file, which is the last thing a thin file needs. Close the newest idle line rather than the oldest, and only if the exposure is what is being read.
Give the file time after that. Our SBI Cashback analysis notes that bureau data can take three to four weeks to update after an approval, and advises first-time applicants to leave roughly six months before a second card. Both are post-approval guidance rather than post-decline rules, but the reporting lag does not change with the outcome. Ninety days is our own minimum honest interval, six months the comfortable one, and in between the useful work is on the report rather than on the form.
Sources
- Reserve Bank of India, notifications index, for the requirement that lenders report credit information to Credit Information Companies at fortnightly rather than monthly intervals with effect from 1 January 2025. Checked 7 September 2026.
- PickMyCard card catalogue, for every eligibility figure and count in this post: income floors, age bands, published score floors and salaried-only flags across the 86 active cards carrying recorded eligibility terms, counted on 7 September 2026.

Frequently asked
What is the minimum income required for a credit card in India?
There is no single figure. Across the 86 active cards in the PickMyCard catalogue that carry recorded eligibility terms, published annual income floors run from ₹1.2 lakh on the AU Spont to ₹30 lakh on the AU Bank Zenith+. Fourteen of those cards state no income floor at all, most of them secured or deposit-linked products where the credit line is backed by a fixed deposit rather than by proven income.
Do banks publish the CIBIL score needed for a credit card?
Almost none do. Only three active cards in our catalogue record a minimum credit score in their published eligibility terms: SBI Card Miles and the Jupiter Edge+ CSB Bank card at 700, and the HDFC Regalia Gold at 750. Every other issuer assesses the credit file without committing to a public cutoff, which is why a score that clears one bank's internal bar can still be declined at another.
Is credit card eligibility different for self-employed applicants?
The income test usually is, because the document changes. The Shoppers Stop HDFC Bank card asks salaried applicants for ₹20,000 a month in net income and self-employed applicants for an ITR above ₹6 lakh, and it runs the age band from 21 to 60 for salaried applicants against 21 to 65 for self-employed ones. HDFC MoneyBack+ pairs a ₹20,000 monthly floor with the same ITR test, though its ₹20,000 is gross rather than net, and it records a single 21 to 60 band for both. Only one active card in our catalogue, the Kredit.Pe Yes Bank ACE, refuses self-employed applicants outright.
Does a rejected credit card application hurt your credit score?
The rejection itself is not reported to the bureaus as an outcome. The enquiry that produced it is, and it stays on the credit report whether the application was approved, declined or withdrawn. One enquiry is unremarkable. Several inside a short window read as an applicant shopping hard for credit, and that pattern is visible to the next issuer in the queue.
How long should you wait after a credit card rejection before applying again?
Long enough for the bureau record to settle and for whatever caused the decline to change. Our SBI Cashback analysis notes that bureau data can take three to four weeks to update after an approval, and advises first-time applicants to leave roughly six months before a second card. Both figures describe the post-approval case rather than a decline, but the reporting lag is the same one, so the interval after a no is sensibly at least as long. Reapplying to the same issuer within days repeats the enquiry without changing any input the model reads.
Card devaluations, reward maths, and rate changes the day they land.
Follow on X
Reader comments
No comments yet. Share your experience with this card below — the first useful comment helps every reader after you.
Comments are moderated before they appear. Share your real experience with a card — what worked, what didn't, what the bank told you. We don't publish promotional content, referral links, or personal financial details. Keep it useful for other readers.