Credit card milestone spends are sold as a reward for loyalty. Priced as arithmetic they are a rebate, and usually a thin one. Cross ₹5,00,000 in a year on the SBI Card PRIME and a ₹7,000 voucher lands, which is 1.40% of the spending that earned it, paid once, up to twelve months after that spending began. Size of the bonus is the wrong number to look at. Bonus divided by the spend the bank demands for it is the right one, and on that measure the rungs in our catalogue run from 10.00% at the top to 0.17% at the bottom.
We priced every milestone rung on every active card that carries both halves of that fraction. Across the 86 active cards in the catalogue, 28 carry a milestone block, and those blocks hold 52 separate entries. Forty-five of the 52 have both a rupee value and a spend threshold, spread across 26 cards, and all 45 are ranked below. The remaining seven are listed too, each with the reason it cannot be priced.
How we price milestone spends in India
Two steps. Convert the bonus into rupees, then divide by the threshold that releases it.
Conversion is trivial where the issuer prints a face value. The BPCL SBI Card Octane pays e-gift vouchers worth ₹2,000 on ₹3,00,000 of annual spending, so that rung returns 0.67%. Ten of the 45 rungs work that way.
Another 35 are quoted in points or miles, and a points bonus is worth only what the points are worth. Our catalogue carries a rupee valuation per point for each card, and we use it. Those 35 rows are marked "(est.)" in the table below, on every row, because the percentage next to them rests on our valuation rather than a figure the bank published. A cardholder who redeems worse than our valuation earns less than the table says.
Spend threshold rewards are not fee waivers, and the two get conflated constantly. A waiver removes a cost already agreed to; a milestone adds value on top. The ICICI Coral Credit Card waives its ₹500 annual fee at ₹1,50,000 of annual spending and pays its first milestone at ₹2,00,000, two thresholds doing two different jobs. We worked through when a spend-linked waiver is worth targeting in our guide to fee waivers, and a waiver is worth chasing far more often, because the saving is certain and the sum is simpler.
One caveat on stacked ladders. Where a card pays a second bonus at a higher threshold, dividing that bonus by the full threshold understates it, because the first rung has already paid out along the way. We report bonus divided by trigger threshold throughout, since that is the figure a cardholder aiming at a rung actually faces, and we give the incremental reading wherever it changes the conclusion. Take the IDFC FIRST Mayura Credit Card. Its second rung is 15,000 reward points at ₹15,00,000, which is 0.25% of the full threshold and ₹3,750 at ₹0.25 a point. Read as an increment, it is ₹3,750 for the ₹7,00,000 of spending above the first rung, or 0.54%. Neither reading makes that ladder worth building a year around, so the table prints the first.
Cadence decides who can reach a rung
A rate means nothing until you know how often the clock resets, and the ranking below mixes five clock speeds: the statement or billing cycle, the calendar month, the quarter, the half year, and the year.
Statement-cycle and calendar-month rungs demand the threshold twelve times over. The American Express Platinum Reserve Credit Card pays a ₹1,000 gift voucher in every calendar month the cardholder puts ₹50,000 of qualifying spend through the card, which is 2.00% a month and ₹12,000 a year against ₹6,00,000 of spending. Enrollment is mandatory, and an unenrolled cardholder who spends the ₹50,000 collects nothing. Axis Rewards Credit Card runs the same shape lower down, 1,500 EDGE Reward points on ₹30,000 per statement cycle, worth ₹300 at ₹0.20 a point, for 1.00%.
AU Bank Altura Plus sits at the small end of the monthly clock: 500 bonus Reward Points on ₹20,000 of retail spend in a calendar month, worth ₹125 at ₹0.25 a point, for 0.63%. Run it all twelve months and the year yields ₹1,500 against ₹2,40,000 of spending, which is the same 0.63%. Cadence changes the effort, never the rate.
Quarterly rungs demand it four times. The HDFC Bank Diners Club Privilege Credit Card pays a ₹1,500 voucher on ₹1,50,000 of spending each calendar quarter, 1.00% a quarter, ₹6,000 a year on ₹6,00,000. Miss March and the quarter is gone. April does not backfill it.
Annual rungs are a different animal. SBI Card Miles pays 5,000 bonus Travel Credits at ₹5,00,000 of annual spending, and Travel Credits are recorded at ₹1 each, so the bonus is ₹5,000 and the rate is also 1.00%. Identical percentage, completely different profile: one large payment can carry a cardholder most of the way, and a quiet March costs nothing.
Two cadences sit between those. The Kotak League Platinum Credit Card pays on a half-year clock. The BOBCARD Etihad Guest runs three clocks at once, a statement-cycle rung at ₹25,000, a quarterly rung at ₹2,00,000 and an annual rung whose threshold the record does not carry.
Cadence is also the first thing to check once a rung looks worth having. A household already putting ₹50,000 a month through a card collects ₹12,000 a year from the American Express Platinum Reserve ladder for behaviour that was happening anyway, and that is real money. Lumpy spenders should ignore every statement-cycle and quarterly rung and look only at annual ones, like the ₹7,000 SBI Card PRIME voucher at ₹5,00,000 or the first IndiGo Axis Bank Premium rung at ₹2,00,000, both of which survive a quiet March.
The rungs above 1.5%, and the one we do not trust
Five of the 45 rungs clear 1.5%, and exactly one clears 3%.
BookMyShow RBL Bank Play Credit Card pays two tickets worth up to ₹250 each, capped at ₹500 a month, for ₹5,000 of eligible spend in a billing cycle. ₹500 against ₹5,000 is 10.00%, five times anything else on the list. Three conditions keep it honest. Its cap is ₹500 a month, so the annual ceiling is ₹6,000 on ₹60,000 of qualifying spend. Redemption requires a single BookMyShow booking of at least two tickets, so the benefit is worthless to somebody who does not go out. And our record carries no general earn rate on the card at all, which makes the ladder close to the whole product.
Then a problem. Kotak League Platinum and American Express Platinum Reserve both price at 2.00%, and the Kotak figure rests on a record that disagrees with itself. Its structured reward value is ₹0.25 a point, which turns 10,000 Reward Points on ₹1,25,000 of half-yearly spend into ₹2,500 and 2.00%. The same record's welcome text describes 5,000 Reward Points as "worth ~₹500", which works out to ₹0.10 a point. At ₹0.10 that rung is ₹1,000 on ₹1,25,000, or 0.80%, and the card drops from joint second to the bottom third of the table. Our rule is that the structured field wins, so 2.00% is what the table prints, but the two readings differ by 2.5x and anybody weighing this card deserves to know the record cannot make up its mind. Kotak also offers four PVR tickets per half year instead of the points, and no rupee value is recorded for those, so that branch cannot be priced at all.
Below them, the American Express Platinum Charge Card and the first HDFC Marriott Bonvoy rung both land on 1.75%. American Express pays renewal vouchers worth up to ₹35,000 at ₹20,00,000 of membership-year spending, against a ₹66,000 fee plus 18% GST, roughly ₹77,880 all in. Marriott pays a Free Night Award worth up to 15,000 Bonvoy points at ₹6,00,000, which is ₹10,500 at the ₹0.70 a point we record. Both headline figures are ceilings rather than expectations. A night booked at 9,000 points is ₹6,300 and that rung collapses to 1.05%.
Where a bonus is quoted as "up to" something, our table prints the ceiling and this paragraph prints the floor, because only the ceiling ever reaches a brochure. Anyone budgeting around a Free Night Award should assume the 1.05% reading until a specific hotel night proves otherwise.
Two more sit just under. SBI Card PRIME pays ₹7,000 at ₹5,00,000 for 1.40%, and the RBL Bank World Safari Credit Card pays a ₹10,000 gift voucher at ₹7,50,000 for 1.33%. Both are printed face values, which makes them the most reliable numbers near the top of the ranking. RBL Bank World Safari charges ₹3,000 a year with no spend-based waiver on record, so the ₹10,000 voucher clears the fee more than three times over for anybody already spending ₹7,50,000. SBI Card PRIME charges ₹2,999 and reverses it at ₹3,00,000, well below its own ₹5,00,000 milestone, so a cardholder who reaches the voucher has already stopped paying for the card.
Long ladders decay, and the floor is lower than the brochures suggest
Where a card stacks rung on rung, the return falls at every step, because the bonus stays flat while the threshold climbs.
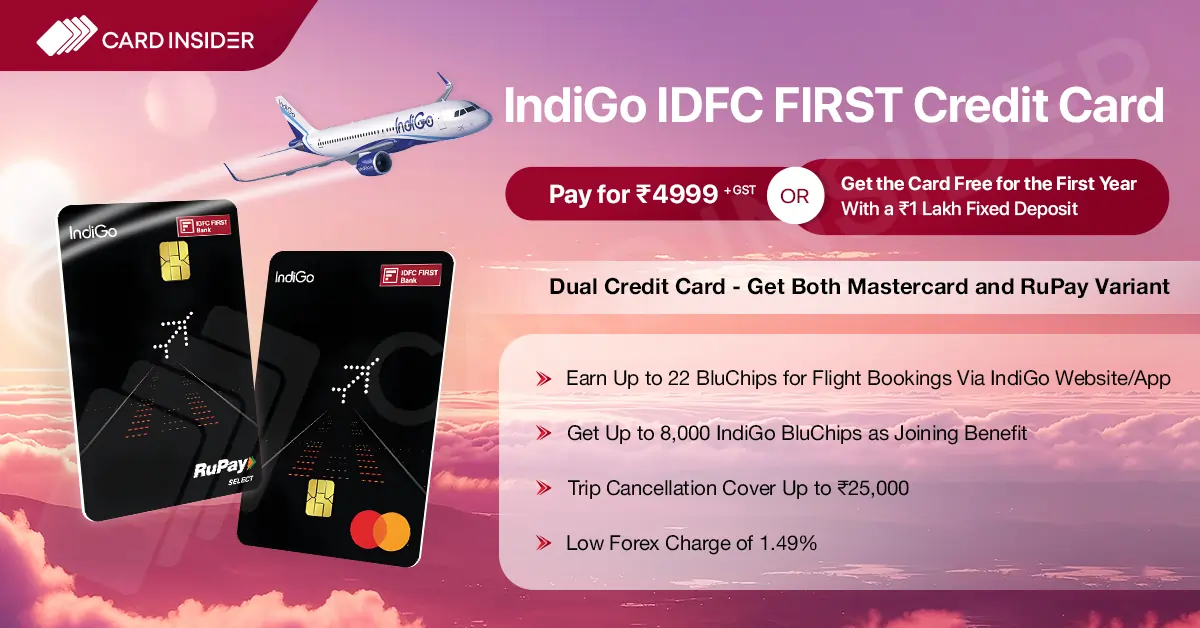
The IndiGo IDFC FIRST Dual Credit Card is the clearest case in the catalogue, and the one that sets the floor. It pays 5,000 IndiGo BluChips at ₹2,00,000 of annual spending and another 5,000 at each of ₹5,00,000, ₹8,00,000, ₹10,00,000 and ₹12,00,000. BluChips are recorded at ₹0.40 on this card, so every rung is worth ₹2,000. Divide ₹2,000 by each threshold in turn and the ladder returns 1.00%, 0.40%, 0.25%, 0.20% and 0.17%. That last figure, ₹2,000 against ₹12,00,000, is the weakest priceable rung on any active card we hold, and the card charges ₹4,999 a year with no spend-based fee waiver on record.
IndiGo Axis Bank Premium Credit Card decays the same way at a different point value. 5,000 BluChips at ₹0.50 is ₹2,500, paid at ₹2,00,000, ₹5,00,000, ₹8,00,000 and ₹12,00,000, so the rungs return 1.25%, 0.50%, 0.31% and 0.21%. Taken whole, 20,000 BluChips is ₹10,000 against ₹12,00,000, or 0.83%. The cheaper IndiGo Axis Bank Credit Card pays 1,200 BluChips at ₹1,50,000 and another 1,200 at ₹3,00,000, ₹600 a tranche at ₹0.50, for 0.40% and 0.20%. Note that our catalogue values a BluChip at ₹0.40 on the IDFC FIRST card and ₹0.50 on the two Axis cards, which is a difference in the record rather than in the currency. We set the three IndiGo cards against each other in our IndiGo card comparison, and read alongside this ranking, the milestone ladders are not where any of them earns its fee.
The IDFC FIRST Mayura Credit Card is the most instructive failure, because its bonus genuinely is large. 7,500 bonus reward points at ₹8,00,000 and 15,000 at ₹15,00,000, at ₹0.25 a point, are ₹1,875 and ₹3,750, or 0.23% and 0.25%. Spend fifteen lakh rupees in a year to collect the whole ladder and ₹5,625 of points arrives, against a ₹5,999 annual fee that carries no recorded spend waiver.
Two shorter ladders misbehave in opposite directions. ICICI Coral pays 2,000 Reward Points at ₹2,00,000 of calendar-year spending, then 1,000 more for every additional ₹1,00,000, worth ₹500 and ₹250 at ₹0.25 a point. Both rungs price at 0.25%, so that ladder is flat rather than decaying, and flat at a quarter of a percent. AU NoMo runs 500 Reward Points at ₹25,000 of quarterly retail spend and another 500 at ₹50,000, ₹125 a rung either way, which halves the return from 0.50% to 0.25% in a single step.
Decay is not universal. RBL Bank World Safari runs 1.00% at ₹2,50,000, drops to 0.75% at ₹5,00,000, then climbs back to 1.33% at ₹7,50,000, because the top rung switches from 15,000 Reward Points to a ₹10,000 voucher. The HDFC Regalia Gold Credit Card does the reverse: a quarterly ₹1,500 voucher at 1.00%, an annual ₹5,000 voucher at ₹5,00,000 also at 1.00%, and a second ₹5,000 voucher at ₹7,50,000 that pays the same money for two and a half lakh rupees more of spending, dropping to 0.67%.
Here is the test that settles most of these cases. If reaching a rung needs money that would not otherwise have been spent, the rung has to beat the whole value of that money, not the base earn rate. Nothing under 1% comes close. Twenty-eight of the 45 rungs fail that test outright.
Every priceable rung, ranked
Start with what is missing. Seven of the 52 milestone entries on active cards never reach the ranking, because one half of the fraction does not exist in the record and guessing at it would defeat the exercise:
- SBI Card PRIME's Pizza Hut e-Voucher at ₹50,000 of spend has a threshold and no recorded rupee value.
- AU Bank Zenith Credit Card's birthday bonus Reward Points carry neither a point count nor a spend threshold.
- Axis Horizon Credit Card credits 1,500 EDGE Miles annually from year two, worth ₹1,500 at ₹1 a mile, but no spend threshold is attached, so no return can be computed.
- The 12,000-mile annual milestone on the BOBCARD Etihad Guest and the 24,000-mile annual milestone on the BOBCARD Etihad Guest Premium are both recorded without the annual spend figures that trigger them.
- One extra domestic lounge visit per ₹1,00,000 of spending on SBI Card Miles, beyond the base four, has no recorded rupee value.
- SBI Card Miles reverses its ₹1,499 annual fee at ₹6,00,000 of annual spending, which is a waiver rather than a bonus, so it is priced nowhere here.
Two further caveats live inside the ranking rather than outside it. Kotak League Platinum's four PVR tickets, offered in place of 10,000 Reward Points, carry no recorded value, so only the points branch is ranked. And both BOBCARD Etihad Guest cards' statement-cycle rungs require four or more transactions as well as the rupee total, a condition no percentage can show.
Where the record gives a brand name and no rupee figure, we would not assign one. A Pizza Hut voucher at ₹50,000 of spending might be worth ₹200 or ₹2,000, which is the difference between 0.40% and 4.00%, too wide a gap to paper over with an estimate.
Forty-five rungs across 26 active cards carry both a rupee value and a spend threshold. All 45 are here, in one list rather than split by cadence, ranked by bonus divided by trigger threshold, with every cadence the record uses shown in the last column. Rows marked "(est.)" are priced from our catalogue's point valuation rather than an issuer-published rupee figure, so the percentage beside them moves if the redemption rate does. Ties are broken alphabetically, not by our preference.
| Card | Milestone rung | Bonus value | Spend needed | Return | Cadence |
|---|---|---|---|---|---|
| BookMyShow RBL Bank Play | 2 tickets up to ₹250 each | ₹500 | ₹5,000 | 10.00% | Billing cycle |
| Amex Platinum Reserve | ₹1,000 gift voucher | ₹1,000 | ₹50,000 | 2.00% | Calendar month |
| Kotak League Platinum | 10,000 Reward Points | ₹2,500 (est.) | ₹1,25,000 | 2.00% | Half year |
| Amex Platinum Charge | Renewal vouchers up to ₹35,000 | ₹35,000 | ₹20,00,000 | 1.75% | Membership year |
| HDFC Marriott Bonvoy | Free Night Award 1 | ₹10,500 (est.) | ₹6,00,000 | 1.75% | Anniversary year |
| SBI Card PRIME | ₹7,000 e-gift voucher | ₹7,000 | ₹5,00,000 | 1.40% | Year |
| RBL Bank World Safari | ₹10,000 gift voucher | ₹10,000 | ₹7,50,000 | 1.33% | Year |
| IndiGo Axis Bank Premium | 5,000 BluChips, rung 1 | ₹2,500 (est.) | ₹2,00,000 | 1.25% | Year |
| HDFC Marriott Bonvoy | Free Night Award 2 | ₹10,500 (est.) | ₹9,00,000 | 1.17% | Anniversary year |
| Axis Rewards | 1,500 EDGE Reward points | ₹300 (est.) | ₹30,000 | 1.00% | Statement cycle |
| HDFC Diners Club Privilege | ₹1,500 brand voucher | ₹1,500 | ₹1,50,000 | 1.00% | Quarter |
| HDFC Regalia Gold | ₹1,500 Myntra or Nykaa voucher | ₹1,500 | ₹1,50,000 | 1.00% | Quarter |
| HDFC Regalia Gold | ₹5,000 SmartBuy voucher, rung 1 | ₹5,000 | ₹5,00,000 | 1.00% | Year |
| IndiGo IDFC FIRST Dual | 5,000 BluChips, rung 1 | ₹2,000 (est.) | ₹2,00,000 | 1.00% | Year |
| RBL Bank World Safari | 10,000 Reward Points | ₹2,500 (est.) | ₹2,50,000 | 1.00% | Year |
| SBI Card Miles | 5,000 Travel Credits | ₹5,000 (est.) | ₹5,00,000 | 1.00% | Year |
| YES BANK POP-CLUB | 1,500 POPcoins | ₹1,500 (est.) | ₹1,50,000 | 1.00% | Year |
| BOBCARD Etihad Guest Premium | 4,000 Etihad Guest miles | ₹2,800 (est.) | ₹3,00,000 | 0.93% | Quarter |
| HSBC TravelOne | 10,000 bonus reward points | ₹10,000 (est.) | ₹12,00,000 | 0.83% | Year |
| RBL Bank World Safari | 15,000 Reward Points | ₹3,750 (est.) | ₹5,00,000 | 0.75% | Year |
| BOBCARD Etihad Guest | 250 miles, 4+ transactions | ₹175 (est.) | ₹25,000 | 0.70% | Statement cycle |
| BOBCARD Etihad Guest | 2,000 Etihad Guest miles | ₹1,400 (est.) | ₹2,00,000 | 0.70% | Quarter |
| BOBCARD Etihad Guest Premium | 500 miles, 4+ transactions | ₹350 (est.) | ₹50,000 | 0.70% | Statement cycle |
| HDFC Marriott Bonvoy | Free Night Award 3 | ₹10,500 (est.) | ₹15,00,000 | 0.70% | Anniversary year |
| BPCL SBI Card Octane | ₹2,000 e-gift vouchers | ₹2,000 | ₹3,00,000 | 0.67% | Year |
| HDFC Regalia Gold | ₹5,000 SmartBuy voucher, rung 2 | ₹5,000 | ₹7,50,000 | 0.67% | Year |
| RBL Bank IndianOil Xtra | 1,000 bonus Fuel Points | ₹500 (est.) | ₹75,000 | 0.67% | Quarter |
| Shoppers Stop HDFC Bank | 500 RP, single weekend purchase | ₹100 (est.) | ₹15,000 | 0.67% | Monthly, 5 a year |
| AU Bank Altura Plus | 500 bonus Reward Points | ₹125 (est.) | ₹20,000 | 0.63% | Calendar month |
| AU NoMo | 500 Reward Points, rung 1 | ₹125 (est.) | ₹25,000 | 0.50% | Quarter |
| IndiGo Axis Bank Premium | 5,000 BluChips, rung 2 | ₹2,500 (est.) | ₹5,00,000 | 0.50% | Year |
| IndiGo Axis Bank | 1,200 BluChips, rung 1 | ₹600 (est.) | ₹1,50,000 | 0.40% | Year |
| IndiGo IDFC FIRST Dual | 5,000 BluChips, rung 2 | ₹2,000 (est.) | ₹5,00,000 | 0.40% | Year |
| AU Bank Zenith+ | Up to 1,000 bonus Reward Points | ₹250 (est.) | ₹75,000 | 0.33% | Statement cycle |
| IndiGo Axis Bank Premium | 5,000 BluChips, rung 3 | ₹2,500 (est.) | ₹8,00,000 | 0.31% | Year |
| AU NoMo | 500 Reward Points, rung 2 | ₹125 (est.) | ₹50,000 | 0.25% | Quarter |
| ICICI Coral | 2,000 bonus Reward Points | ₹500 (est.) | ₹2,00,000 | 0.25% | Calendar year |
| ICICI Coral | 1,000 RP per extra ₹1,00,000 | ₹250 (est.) | ₹1,00,000 | 0.25% | Calendar year |
| IDFC FIRST Mayura | 15,000 bonus reward points | ₹3,750 (est.) | ₹15,00,000 | 0.25% | Year |
| IndiGo IDFC FIRST Dual | 5,000 BluChips, rung 3 | ₹2,000 (est.) | ₹8,00,000 | 0.25% | Year |
| IDFC FIRST Mayura | 7,500 bonus reward points | ₹1,875 (est.) | ₹8,00,000 | 0.23% | Year |
| IndiGo Axis Bank Premium | 5,000 BluChips, rung 4 | ₹2,500 (est.) | ₹12,00,000 | 0.21% | Year |
| IndiGo Axis Bank | 1,200 BluChips, rung 2 | ₹600 (est.) | ₹3,00,000 | 0.20% | Year |
| IndiGo IDFC FIRST Dual | 5,000 BluChips, rung 4 | ₹2,000 (est.) | ₹10,00,000 | 0.20% | Year |
| IndiGo IDFC FIRST Dual | 5,000 BluChips, rung 5 | ₹2,000 (est.) | ₹12,00,000 | 0.17% | Year |
What we would actually do
Treat every rung under 1% as though it does not exist. That single rule removes the twenty-eight rows named above and costs almost nothing, because a rung paying 0.23% on eight lakh rupees is not a benefit anybody should reorganise their spending around.
And where the record contradicts itself, as it does on Kotak League Platinum, assume the worse reading until the bank publishes otherwise. Our table prints 2.00% because the structured field is the one we treat as authoritative, but a cardholder who redeems 10,000 Reward Points and receives ₹1,000 rather than ₹2,500 will have found the answer the expensive way. At that price the rung is 0.80% and the card belongs near the bottom of the ranking rather than the top. Milestone spends reward the spending you were doing anyway, and they punish anyone who moves spending to reach them.
Sources
- pickmycard.in card catalogue, verified against issuer Most Important Terms and Conditions documents. Source of every fee, threshold, bonus quantum and point value above. Catalogue
verifiedAtdates for the cards cited: SBI Card PRIME 2026-05-05, Axis Horizon 2026-05-10, AU Altura Plus 2026-05-13, SBI Card Miles 2026-05-14, both BOBCARD Etihad Guest cards 2026-05-27, HDFC Regalia Gold 2026-05-29, HDFC Diners Club Privilege 2026-06-01, RBL IndianOil Xtra 2026-06-11, ICICI Coral, Kotak League Platinum, Axis Rewards, BPCL SBI Card Octane, YES BANK POP-CLUB, Shoppers Stop HDFC, AU Zenith, AU Zenith+, AU NoMo, IDFC FIRST Mayura, RBL World Safari, HDFC Marriott Bonvoy and BookMyShow RBL Play 2026-07-02, Amex Platinum Reserve 2026-07-08, Amex Platinum Charge 2026-07-23, IndiGo IDFC FIRST Dual, IndiGo Axis Bank and IndiGo Axis Bank Premium 2026-08-03, HSBC TravelOne 2026-08-06. Checked 14 September 2026. - SBI Card, https://www.sbicard.com, source of the BPCL SBI Card Octane, SBI Card PRIME and SBI Card Miles fee and milestone terms. Checked 14 September 2026.
- Kotak Mahindra Bank, https://www.kotak.bank.in, source of the Kotak League Platinum half-yearly milestone structure and of the welcome-bonus wording that values 5,000 Reward Points at about ₹500. Checked 14 September 2026.
- HDFC Bank, https://www.hdfc.bank.in, source of the HDFC Regalia Gold, HDFC Marriott Bonvoy, Shoppers Stop HDFC Bank and HDFC Bank Diners Club Privilege milestone terms. Checked 14 September 2026.
- American Express India, https://www.americanexpress.com/in/, source of the Platinum Reserve monthly voucher terms and the Platinum Charge renewal voucher and fee terms. Checked 14 September 2026.
- IDFC FIRST Bank, https://www.idfcfirst.bank.in, source of the IDFC FIRST Mayura and IndiGo IDFC FIRST Dual bonus thresholds. Checked 14 September 2026.
- Axis Bank, https://www.axis.bank.in, source of the IndiGo Axis Bank, IndiGo Axis Bank Premium, Axis Rewards and Axis Horizon milestone terms. Checked 14 September 2026.
- RBL Bank, https://www.rbl.bank.in, source of the BookMyShow RBL Bank Play, RBL Bank World Safari and RBL Bank IndianOil Xtra milestone terms. Checked 14 September 2026.
- ICICI Bank, https://www.icici.bank.in, source of the ICICI Coral fee waiver and calendar-year milestone terms. Checked 14 September 2026.
- AU Small Finance Bank, https://www.au.bank.in, source of the AU Bank Altura Plus, AU NoMo, AU Bank Zenith and AU Bank Zenith+ milestone terms. Checked 14 September 2026.
- YES BANK, https://www.yes.bank.in, source of the YES BANK POP-CLUB annual milestone and fee waiver terms. Checked 14 September 2026.
- BOBCARD, https://www.bobcard.co.in, source of both BOBCARD Etihad Guest milestone sets. The 12,000-mile and 24,000-mile annual milestones are recorded without spend thresholds, which we could not confirm. Checked 14 September 2026.
- HSBC India, https://www.hsbc.co.in, source of the HSBC TravelOne annual bonus point threshold. Checked 14 September 2026.
Disclosure: this post contains affiliate links. If you apply through them we may earn a commission, at no extra cost to you. Our editorial view is independent of that. #ad

Frequently asked
What are milestone spends on a credit card?
Milestone spends are spending thresholds a card sets, and crossing one releases a bonus: a voucher, points, or miles. The clock can be a statement cycle, a month, a quarter, a half year or an anniversary year. The bonus sits on top of whatever the card already pays per transaction.
Are credit card milestone benefits worth chasing?
Only when the spending was already going to happen. Dividing each priceable bonus by the spend that triggers it gives returns from 0.17% to 10.00% across 45 rungs, and 28 of those sit below 1%. Pushing an extra ₹1,50,000 through a card to collect ₹600 of points costs far more than it returns.
What is the difference between a quarterly and an annual spend milestone?
A quarterly milestone resets every three months, so it demands sustained spending at the threshold rate all year. An annual milestone counts anniversary-year or calendar-year spending and can be cleared in one heavy month. The HDFC Regalia Gold Credit Card carries both, a ₹1,500 quarterly voucher and two annual rungs.
Which Indian credit card has the best milestone benefit?
By return per rupee, the BookMyShow RBL Bank Play Credit Card, which pays up to ₹500 of tickets for ₹5,000 of eligible spend in a billing cycle, a 10.00% return. Its ceiling is ₹500 a month, so the benefit stays small in absolute terms even though the rate is high.
Which credit card milestone pays the least in India?
The top rung of the IndiGo IDFC FIRST Dual Credit Card. It pays 5,000 IndiGo BluChips, worth ₹2,000 at our recorded ₹0.40 a BluChip, for ₹12,00,000 of annual spending, a return of 0.17%. Four lower rungs on the same card pay 1.00%, 0.40%, 0.25% and 0.20%.
Card devaluations, reward maths, and rate changes the day they land.
Follow on X
Reader comments
No comments yet. Share your experience with this card below — the first useful comment helps every reader after you.
Comments are moderated before they appear. Share your real experience with a card — what worked, what didn't, what the bank told you. We don't publish promotional content, referral links, or personal financial details. Keep it useful for other readers.