IDFC FIRST Bank charged 3.5% on foreign currency spends on most of its credit cards until 8 September 2026. From 9 September 2026 it charges nothing, on any card, for new and existing customers alike. The bank announced the move at the Global Fintech Fest in Mumbai, and its own forex markup page now describes every card in the portfolio as a zero forex markup credit card.
That is the headline. A second date sits underneath it: from 26 October 2026, most IDFC FIRST cards stop earning reward points on international transactions. Both halves matter, because together they change which card belongs in a travel wallet.
From a premium perk to a bank-wide default
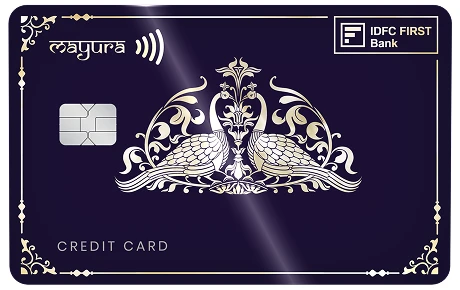
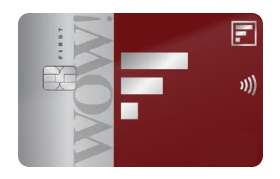
Zero forex has been a specialist feature in India. Issuers attach it to one travel card or one premium card and charge between 0.99% and 3.5% on everything else. IDFC FIRST itself worked that way: Mayura, FIRST Private and FIRST WOW! carried no markup, most of the portfolio sat at 3.5%, and a few cards fell in between.
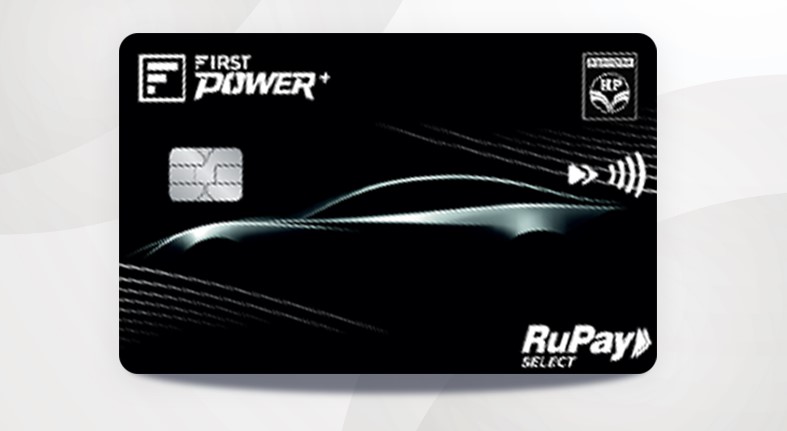
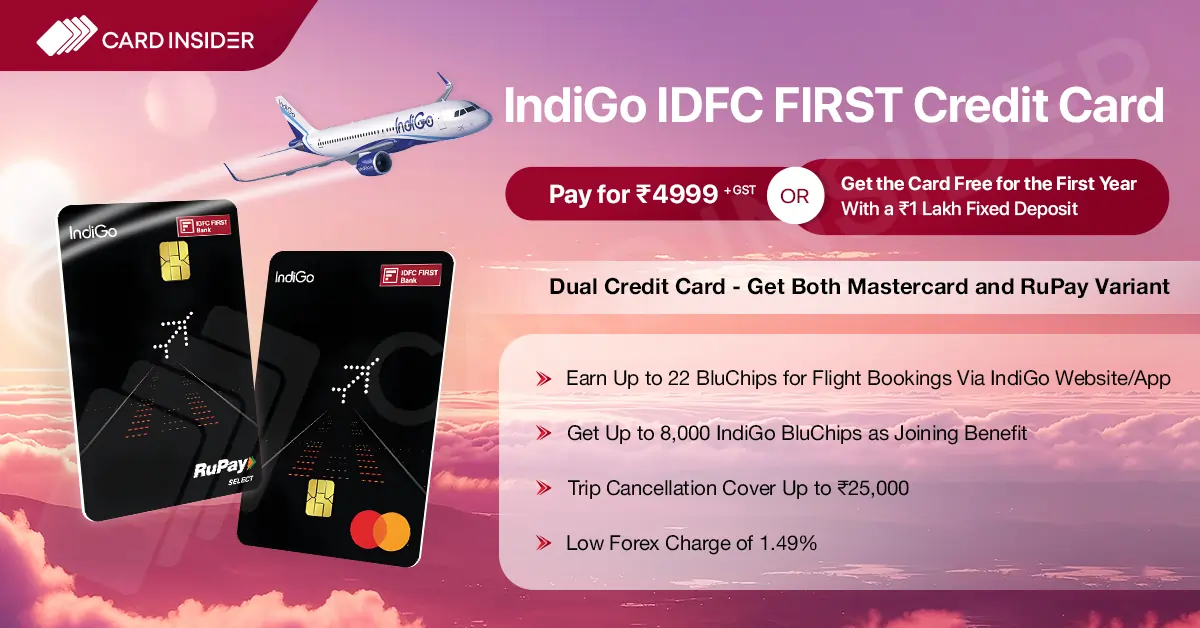
That ladder is now flat. The bank's list covers FIRST Classic, FIRST Millennia, FIRST Select, FIRST Wealth, Ashva, Mayura, Diamond Reserve, FIRST Power and FIRST Power+, the IndiGo IDFC FIRST Dual card, FIRST WOW! and WOW! Black, Hello Cashback, FIRST EARN and the LIC Classic and LIC Select cards. Nothing has to be applied for, upgraded or activated beyond the usual step of enabling international usage in the app.
On a ₹1 lakh overseas trip, a 3.5% markup was ₹3,500, and GST at 18% on that markup took the cost to ₹4,130. That amount is what disappears.
The rewards switch-off on 26 October 2026
The cost of the change arrives seven weeks later. From 26 October 2026, international transactions on most IDFC FIRST cards earn no reward points. Seven cards are carved out and keep earning abroad: Ashva, IndiGo, Mayura, FIRST Private, FIRST WOW!, FIRST WOW! Black and Gaj.
For a holder of one of the other cards, the trade is simple to price. FIRST Wealth, for example, earns one reward point per ₹200 at its base rate and values a point at ₹0.25, which is a 0.125% return. Ten times that rate is 1.25%. Either figure is smaller than the 4.13% that the markup and its GST used to cost, so a card that now returns nothing and charges nothing abroad still leaves its holder ahead.
For holders of the seven exempt cards, nothing is given up at all. The IDFC FIRST Mayura and FIRST WOW! were zero markup before and continue to earn on international spends after 26 October.
Who should rethink their travel card
Anyone holding a lifetime free IDFC FIRST card now owns a zero forex card without having asked for one. For one or two foreign trips a year, plus subscriptions billed in dollars, that removes most of the reason to apply for a separate travel card only for the markup.
A dedicated travel card still earns its place when it pays meaningfully on foreign spends or carries lounge access and transfer partners. The comparison has shifted, though. The alternative is no longer a card charging 3.5%. It is a free card charging 0%, so a travel card has to win on rewards and benefits alone. Our piece on zero forex markup versus lounge access walks through that choice.
Two habits still matter on any zero markup card. Pay in the local currency when a terminal offers rupees, because Dynamic Currency Conversion replaces the network rate with the merchant's own. And check the statement: IDFC FIRST shows any markup as a separate line item, so a charge that should not be there is easy to spot.
Where this leaves a travel wallet
Holders of a non-exempt IDFC FIRST card should move foreign currency spends to it now and ignore the reward points they stop earning in October, because the markup saving is larger than those points were. Holders of Mayura, WOW!, Ashva or the IndiGo card change nothing. Anyone about to apply for a paid card mainly to avoid forex markup should first check whether an IDFC FIRST card is already in the drawer.
Sources
Frequently asked
Which IDFC FIRST credit cards have zero forex markup?
All of them. IDFC FIRST Bank's forex markup page now lists every card in the portfolio as zero markup, including FIRST Classic, FIRST Millennia, FIRST Select, FIRST Wealth, Ashva, Mayura, FIRST Power, FIRST Power+, the IndiGo IDFC FIRST Dual card, FIRST WOW!, Hello Cashback, FIRST EARN and the LIC co-branded cards. The change took effect on 9 September 2026.
Do existing IDFC FIRST cardholders need to do anything to get zero forex markup?
No. It applies automatically to existing cards as well as new ones. There is no new application, upgrade or spend condition. International transactions still have to be switched on in the app or net banking before the first foreign currency payment.
Will IDFC FIRST cards still earn reward points on international spends?
Most will not from 26 October 2026. The cards that keep earning on international transactions are Ashva, IndiGo, Mayura, FIRST Private, FIRST WOW!, FIRST WOW! Black and Gaj.
Does zero forex markup mean a foreign transaction costs nothing extra?
No. The bank's markup is gone, but the card network's exchange rate still applies, and choosing to pay in rupees at an overseas terminal triggers Dynamic Currency Conversion at the merchant's rate, which is usually worse. Paying in the local currency avoids it.
Card devaluations, reward maths, and rate changes the day they land.
Follow on X
Reader comments
No comments yet. Share your experience with this card below — the first useful comment helps every reader after you.
Comments are moderated before they appear. Share your real experience with a card — what worked, what didn't, what the bank told you. We don't publish promotional content, referral links, or personal financial details. Keep it useful for other readers.